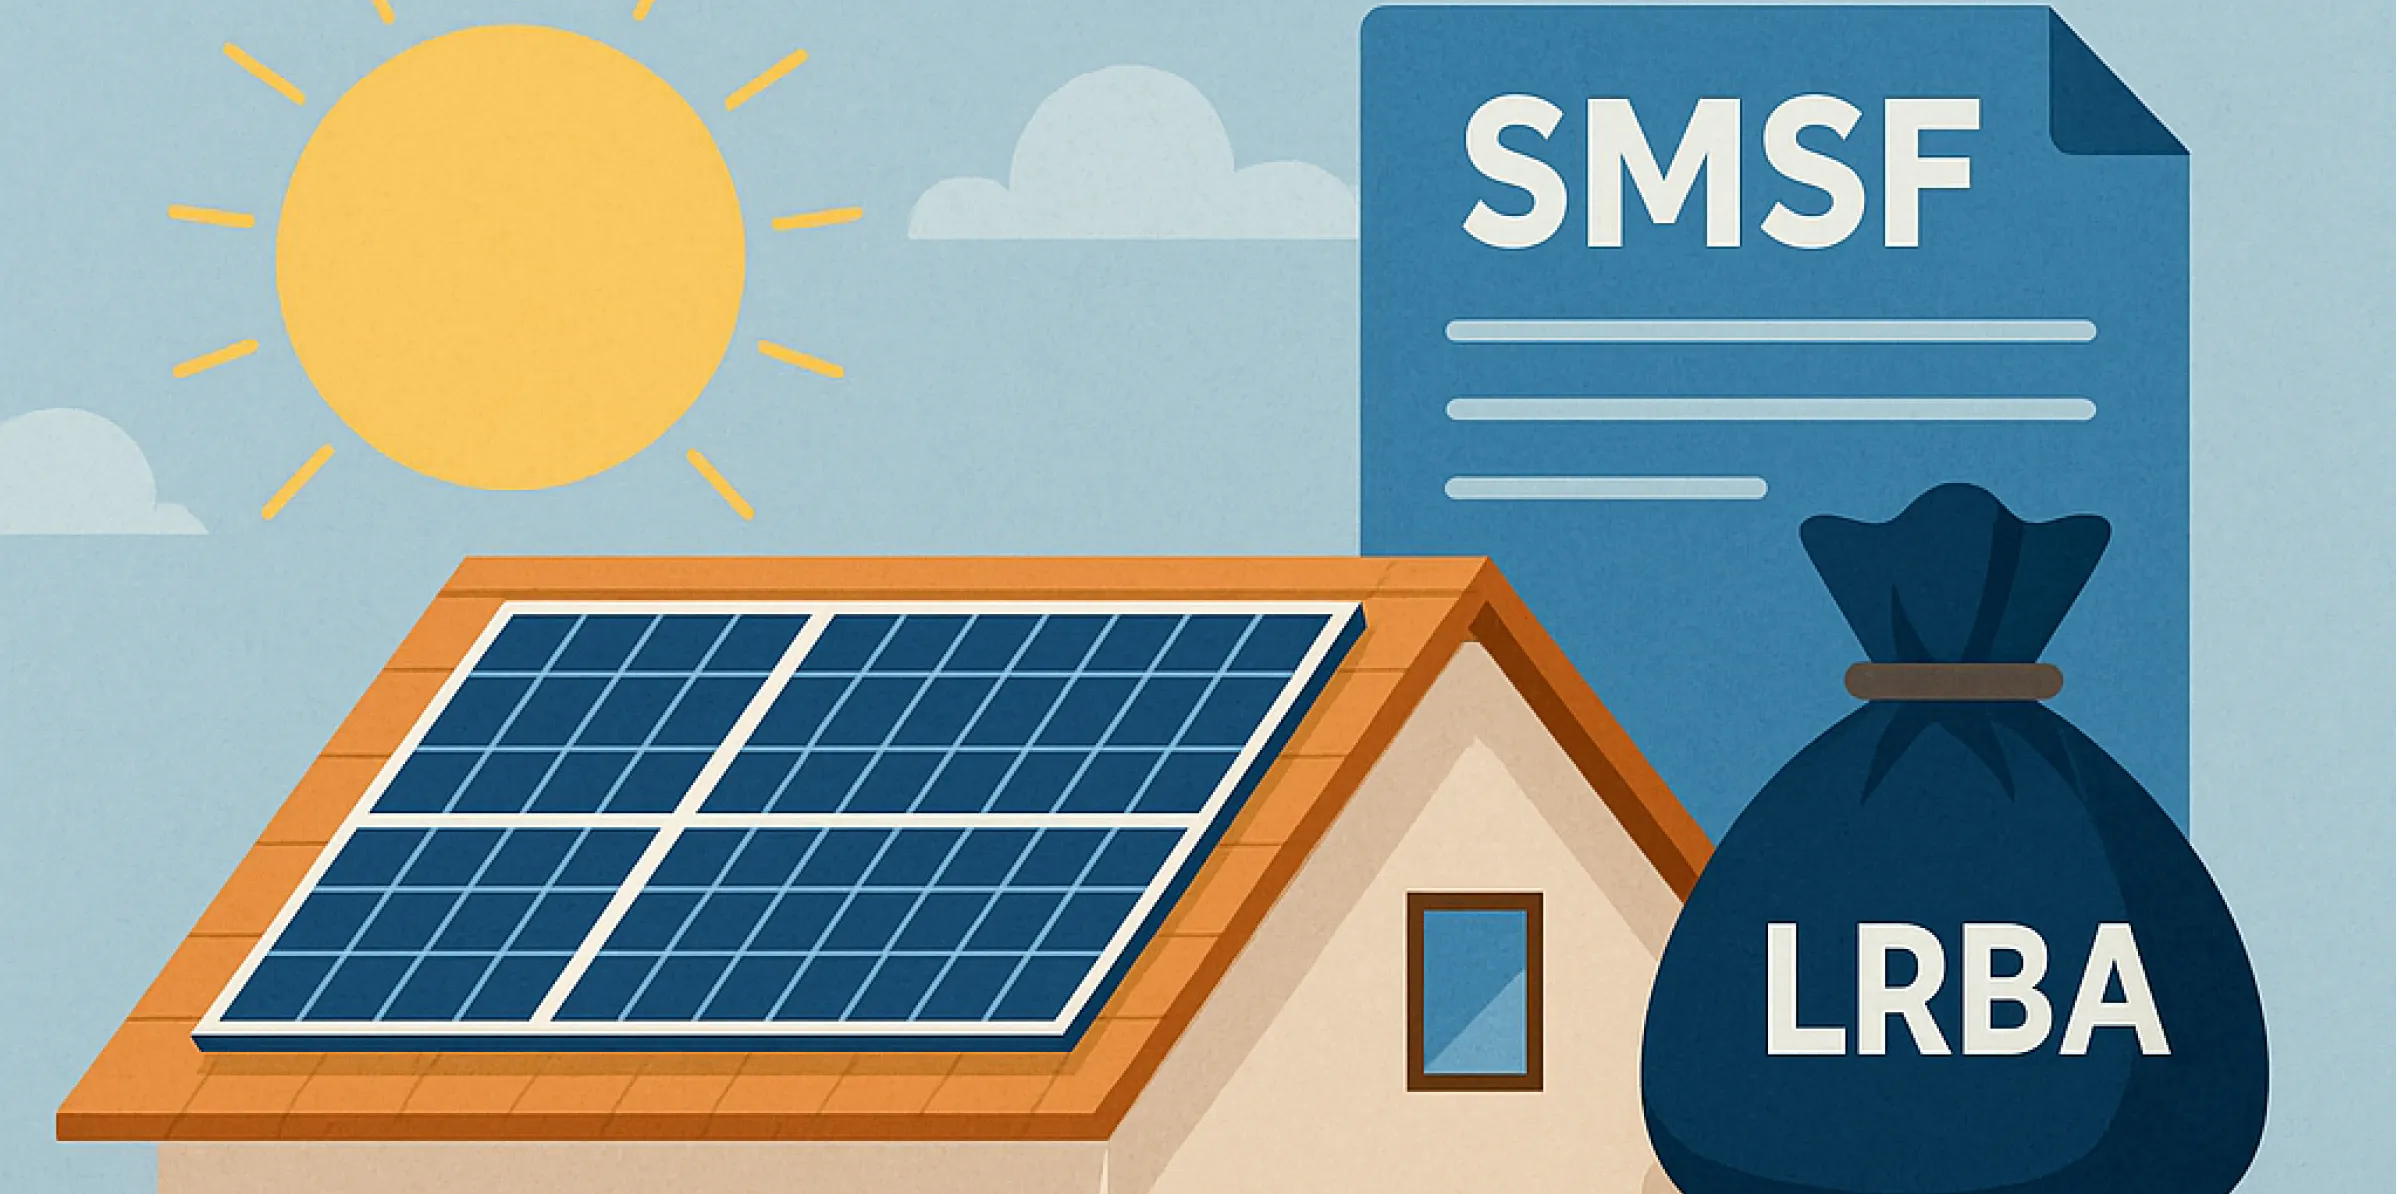
On 23 June 2026, Prime Minister Albanese and Treasurer Chalmers confirmed the government will support an amendment banning SMSFs from entering into new Limited Recourse Borrowing Arrangements (LRBAs) for residential property. In plain terms, this means SMSFs will no longer be able to take out a loan to buy a residential property inside super.
The amendment was the condition for Greens' Senate support on the broader capital gains tax and negative gearing reform package.
Here's what we know so far.
If you already have a residential loan in your SMSF
Your existing arrangement is not affected. All current loans are fully grandfathered, which means your loan continues on its existing terms until it's paid off or the property is sold. Nothing changes.
If you're partway through a purchase
Contracts exchanged before the ban starts will be protected. There's also a 45-day transition period after the legislation receives royal assent.
The timeline
- Senate vote expected before parliament rises, around 2 July 2026
- Royal assent likely within days of the vote
- Ban takes effect 45 days after royal assent, so roughly mid-August 2026
What SMSFs can still do
The ban is specifically on borrowing to buy residential property. That's an important distinction.
SMSFs can still purchase residential property outright if the fund has the cash to do so without a loan. Commercial property borrowing arrangements are completely unaffected.
One thing worth knowing
Under the broader negative gearing changes coming in July 2027, individuals, trusts, and companies will lose the ability to negatively gear newly purchased existing residential investment properties. SMSFs aren't caught by those particular rules. So an SMSF that buys an existing residential investment property outright can still claim the usual tax deductions against rental income.
The trade-off is that you can no longer borrow to do it. The fund needs to have the money. It's a shift in strategy rather than the end of residential property in super, but it does change the planning.
Disclaimer: This information is general in nature and is provided for informational purposes only. It does not constitute personal financial, tax, or legal advice. You should consider your own circumstances and seek independent professional advice before making any decisions about your SMSF.